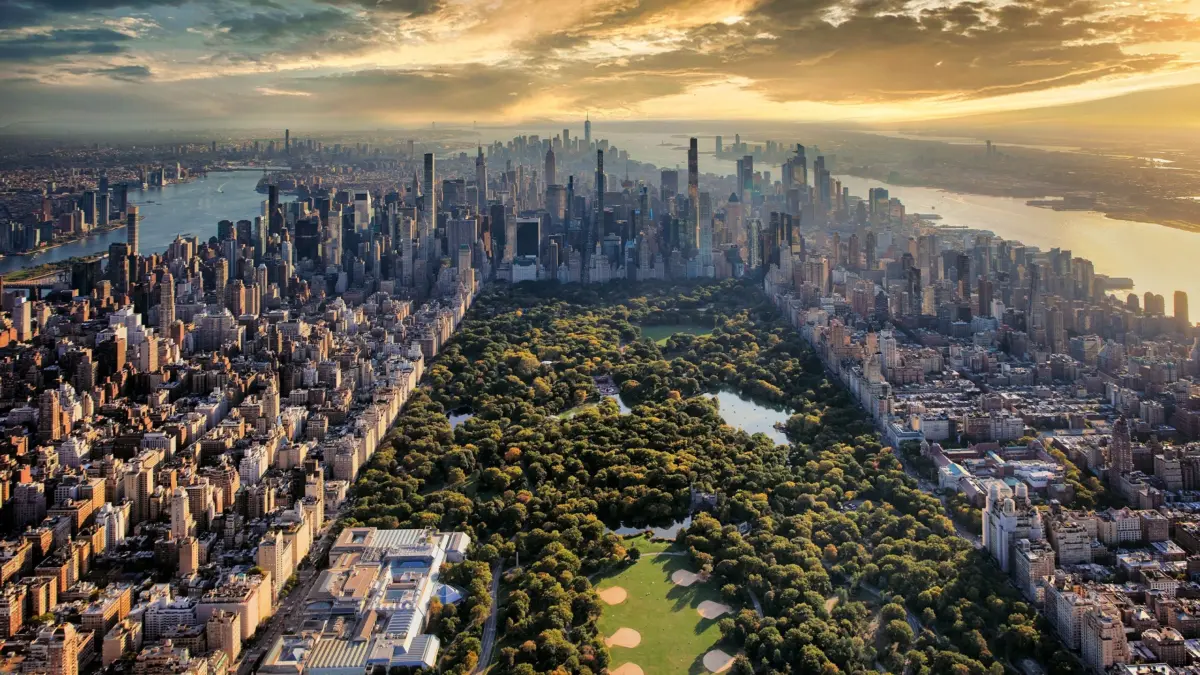
The Manhattan luxury real estate market is experiencing a significant surge, defying expectations and proving remarkably resilient in the face of local regulatory changes, looming tax implementations, and severely constrained inventory. Even as the city navigates the rollout of its controversial new pied-à-terre tax targeting secondary homes valued over $1 million, high-end buyers are stepping forward in droves to secure prime real estate across the borough.
According to the latest market data from the Olshan luxury report, the sector recorded a strong week with 36 contracts signed at $4 million and above. This figure marks an increase of eight more contracts than the previous week and represents the highest volume of high-end sales recorded since the first week of June. Industry experts note that the robust activity underscores enduring confidence in New York City’s premier residential market, demonstrating that affluent buyers remain unfazed by rising local and national tax pressures aimed at high-net-worth individuals.
Market Dynamics: Condos Lead While Co-ops Close the Gap
Geographically, the Upper East Side claimed the crown as the most popular area for luxury buyers last week. As is traditionally the case in Manhattan, condominiums outsold cooperatives, but the historic gap between the two property types narrowed considerably. Condos accounted for 19 sales, edging out co-ops by a margin of only six units.
The persistent preference for condos typically stems from fewer operational hurdles compared to co-ops, which are not only considerably older on average but also enforce notoriously stringent board approval processes. However, co-ops offer a distinct financial advantage in terms of initial cost. Last week, the average asking price for a luxury-level co-op stood at $6.8 million, contrasted with $9.4 million for a condo.
The week’s premier transaction highlighted the immense appetite for top-tier condominium properties. The top-selling property was a sprawling six-bedroom penthouse condo located at 255 East 77th St., carrying an ambitious asking price of $23.75 million, which breaks down to an impressive $4,303 per square foot.
Spanning a rare 5,520 square feet, the residence took a remarkably short five months from its initial listing to securing a signed contract. A major selling point for the property is its sweeping, unobstructed 360-degree views of Central Park from nearly every room, complemented by two expansive private terraces totaling 363 square feet.
The building itself, designed by the renowned architectural firm Robert A.M. Stern Architects, offers an array of ultra-luxury amenities. Residents have access to a door attendant, concierge services, a resident lounge, a children’s playroom, a golf simulator, a library, and an automated parking system. The state-of-the-art fitness center features a dedicated yoga room, a spa equipped with a steam room and sauna, massage and treatment rooms, and a crown jewel 75-foot swimming pool. Alexa Lambert of Compass held the exclusive listing for the property.
Securing the spot for the second-highest sale of the week was a sponsor condo located at 53 W. 53rd St., which boasted an asking price of $21.53 million. The 3,762-square-foot, three-bedroom unit features striking north-facing views of Central Park and remarkably found a buyer on the very same day it was listed, pointing strongly toward a discreet, off-market deal. Michelle Griffith of Douglas Elliman brought the buyer to that transaction.
Luxury Buyers Shrug at the New Pied-à-Terre Tax
The impressive momentum in the luxury housing sector directly contradicts early warnings from critics who predicted a severe market contraction following the implementation of the city’s new pied-à-terre tax on July 1.
The progressive surcharge applies to secondary-home condos and co-ops with fair market values starting at $1 million. Properties valued between $1 million and $3 million face a 4.00% surcharge rate, while those valued from $3 million to $5 million are taxed at 5.25%. Properties valued at $5 million or greater face the highest tier at 6.50%. This annual tax collection is currently scheduled to remain in effect until June 30, 2031.
The rollout of the tax has been notably complex, characterized by administrative delays and ongoing legal challenges. According to local reports, approximately 55% of property owners who have received a tax bill have thus far successfully navigated the appeals process.
Michael Reisor of the Compass-affiliated Reisor Team recently brokered the sale of a $4.5 million loft condo at the Schumacher complex on Bleecker Street in Noho, which will serve as a pied-à-terre. Reisor emphasizes that the new levy is failing to deter wealthy investors from committing capital to Manhattan real estate.
"Every type of product in Manhattan is only going to be getting more expensive as time goes on," Reisor notes. "New York will always be New York. If you’re waiting out news on the pied-à-terre tax, you’re going to be waiting too long, and you won’t be able to catch up with the market."
Furthermore, New York City is not alone in enacting measures to increase tax revenues from affluent residents. Similar legislative efforts are spreading nationwide, pointing to a broader trend. Whether examining California’s proposed Billionaire Tax or Washington State’s Millionaires Tax scheduled to take effect in January 2028, state governments are increasingly looking to bolster public coffers by taxing high earners, leaving elite buyers with fewer geographic alternatives if they wish to sidestep higher fiscal burdens.
"We’re not seeing people not purchase the product they want because of fears of the tax, and the numbers this week reflect that," Reisor explains. "No one is going to throw out New York because of taxes."
According to Reisor, while affluent buyers might occasionally calibrate their budgets slightly, most prefer to maintain their desired lifestyle and secure major physical assets, choosing instead to adjust their spending in other areas if necessary. He cites an instance involving a client who initially considered downgrading from a pied-à-terre townhouse to a less expensive option due to the tax. Ultimately, the buyer abandoned that idea, choosing to prioritize a property that fully met his personal standards and lifestyle requirements.
Wealthy buyers "kind of poke their heads above water, look around, and go, ‘Eh, I’ll deal with the tax,’" Reisor says. "There’s a price to being in Manhattan, one that people deem worth it."
Inventory Constraints and Bidding Wars in the Rental Market
Echoing these observations, Michelle Griffith of Douglas Elliman notes that luxury agents across the board are expressing surprise at the sheer resilience and strength of the current market. She attributes this robust activity to two primary catalysts: an overall lack of inventory and an exorbitant, highly competitive rental market.
"This is lack of inventory across all price points," Griffith explains. "You couple that with rents that are through the roof. That takes people who are living and working in Manhattan, with the kids in school, and pushes them into buying scenarios."
High-end rental apartments that historically commanded monthly rates of $25,000 are increasingly entering heated bidding wars and leasing for nearly double that amount. Consequently, prospective residents who wish to avoid crushing monthly rental expenditures find themselves channeled directly into a purchasing market defined by remarkably slim inventory, which has dropped by nearly 30% this fall.
"For the longest time, people were saying ‘Let’s wait for more inventory to come on the market,’" Griffith says. "We don’t see new inventory."
To navigate these tight conditions, brokers are actively advising clients to compromise on nonessential features rather than waiting for an elusive ideal property. "We’re saying to our clients, ‘Listen, there is no perfect apartment. If it checks 7 out of the 10 boxes, you need to move forward with it.’"
In addition, buyer flexibility has expanded regarding property conditions. While many purchasers previously held out exclusively for turnkey residences, the scarcity of move-in-ready units has shifted buyer sentiment. With premier turnkey homes rapidly disappearing from listings, a growing segment of buyers is openly embracing renovation projects to secure their preferred locations.
This willingness to undertake major renovations is particularly evident in the high demand for prewar co-ops on the Upper East Side. The consistent movement of prewar co-op units demonstrates that buyers are prepared to invest time and capital into renovations to secure prime locations, expansive layouts exceeding 4,000 square feet, and at least three bedrooms.
While the highest-selling co-op last week—a meticulously maintained 1925 five-bedroom residence at 860 Park Ave. with an asking price of $10,950,000—required little intervention, co-ops at the ultra-luxury tier generally demand less initial work. However, Griffith emphasizes that high-end buyers overall are increasingly willing to manage a renovation project if the underlying asset meets their core criteria regarding size, layout, and neighborhood.
"It’s showing long-term commitment to Manhattan," Griffith concludes.