Crypto investors across the United States who failed to properly report digital asset trades in previous years may soon find a clear pathway to compliance, thanks to a legislative measure currently advancing through the US Congress.
The initiative is anchored in Section 502 of the Digital Asset Tax Certainty Act, designated as H.R. 10357. If enacted into law, this provision would require the United States Treasury secretary to establish a dedicated Digital Asset Voluntary Disclosure Program within a 12-month window. This program would grant eligible taxpayers a formalized mechanism to correct past digital asset tax violations by filing amended returns. To resolve their historical liabilities, participants would be required to pay the outstanding tax owed, alongside applicable interest and a structured program penalty.
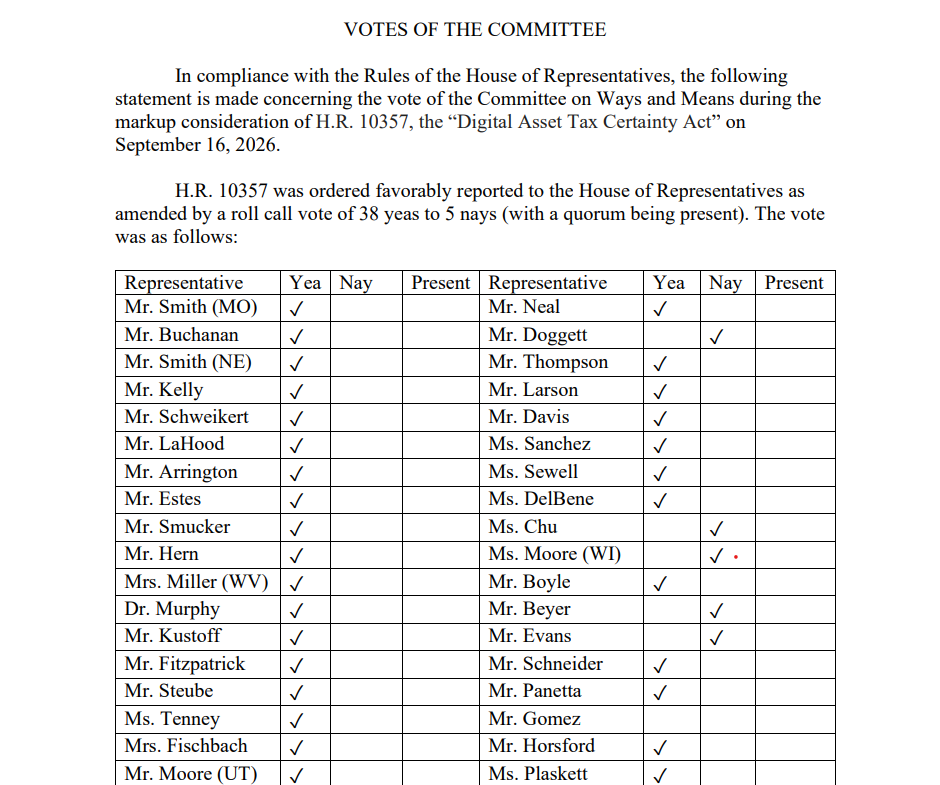
The legislative process surrounding the bill took a significant step forward when the House Ways and Means Committee approved the measure by a vote of 38-5 on Sept. 16. Despite this strong bipartisan committee approval, the measure has not yet become law. It still requires full passage in both the House of Representatives and the Senate before it can be presented to the president for a final signature.
Andrew Gordon, executive director of Digital Asset Tax Action, highlighted the prospective impact of the measure, describing it as a major development that could assist a significant portion of ordinary taxpayers despite currently flying under the radar of broader public attention.
A Gap in the System
The advancement of H.R. 10357 comes at a time when American cryptocurrency investors are actively navigating their first filing season under newly implemented regulatory frameworks. Specifically, the industry is adjusting to the new 1099-DA broker reporting rules, which grant the Internal Revenue Service unprecedented visibility into digital asset transactions.
While industry advocates generally agree that these new broker reporting rules will streamline compliance for future tax years, they do not resolve the regulatory and financial overhang left by previous years before the new reporting mandates took effect. Gordon pointed out that a large share of retail investors failed to report their transactions correctly over the years. Furthermore, existing IRS procedures fail to provide a predictable, standardized mechanism for taxpayers who made honest mistakes to resolve their historical tax liabilities.
According to Gordon, a crypto investor who realizes they have failed to properly report their digital asset activity or omitted it entirely currently lacks a reliable method to fix the issue. Taxpayers frequently discover years down the line that they fundamentally misunderstood the complex tax treatment governing crypto-to-crypto trades, or that they struggled to accurately aggregate and report activity spread across multiple centralized and decentralized platforms.
What Taxpayers Could Get
To understand the necessity of the proposed program, industry experts point to the limitations of existing IRS mechanisms. The agency’s current Voluntary Disclosure Practice is primarily designed for taxpayers who willfully violated tax rules and therefore face potential criminal exposure and severe legal consequences.
For taxpayers who made unintentional errors, correcting past mistakes typically involves filing amended returns. However, the associated penalty treatment under current guidelines remains unpredictable and lacks the clear framework that provision 502 seeks to introduce for digital assets specifically.
Sharon Yip, a certified public accountant and founder of Crypto Tax Advisors, noted that reporting errors among ordinary cryptocurrency investors are remarkably common. Based on her firm’s professional experience, many clients failed to report their crypto transactions simply because they genuinely believed that no tax event occurred until they formally converted their digital assets into fiat currency like US dollars. Others relied on incomplete, fragmented exchange records or incorrectly classified complex transactional types.
Yip emphasized that there is currently no standardized process that affords non-willful crypto investors predictable penalty treatment or a clear path toward financial resolution. She explained that a crypto-specific disclosure program could effectively fill this gap by providing a defined correction period, reduced and predictable penalties, and a much-needed sense of regulatory certainty for taxpayers who choose to come forward voluntarily.
What the Bill Would Offer
Under the terms outlined in Section 502, participating taxpayers would generally be required to file amended returns within 24 months of the program’s official establishment. The bill outlines two distinct penalty tracks depending on the intent and cooperation of the taxpayer.
Significantly lower rates are designated for taxpayers who certify under penalty of perjury that their past reporting violations were neither fraudulent nor willful. Under this non-willful track, participants would face a 0% penalty on the first $25,000 of tax deficiency per year, and a modest 5% penalty on amounts exceeding that threshold, provided they file their amended returns within the first 12 months of the program’s launch.
Conversely, for individuals who do not make this certification, much steeper rates apply. These taxpayers would face a 25% penalty on the first $25,000 of tax deficiency and a 40% penalty on amounts above that level. Furthermore, these penalty rates are structured to increase further if taxpayers miss the initial filing window.
The legislation also provides relief from specified civil penalties. Additionally, taxpayers who decline to certify as non-willful are nonetheless protected from criminal referrals based on information they properly disclose for the specific tax offenses covered under the provision.
Yip advises that taxpayers interested in utilizing the program should proactively review their historical transaction records across various exchanges and digital wallets. This due diligence helps identify which specific tax years require correction and allows individuals to assess whether their past filing errors were genuinely non-willful. Because making a false certification carries severe legal consequences under the penalty of perjury, she strongly recommends seeking professional guidance for anyone who remains uncertain about their tax standing.
The potential implementation of Section 502 arrives as welcome news for many American crypto participants, particularly given widespread confusion regarding tax obligations. A report published by CoinTracker and Coinbase found that only 49% of crypto users correctly understood that selling cryptocurrency can constitute a taxable event.