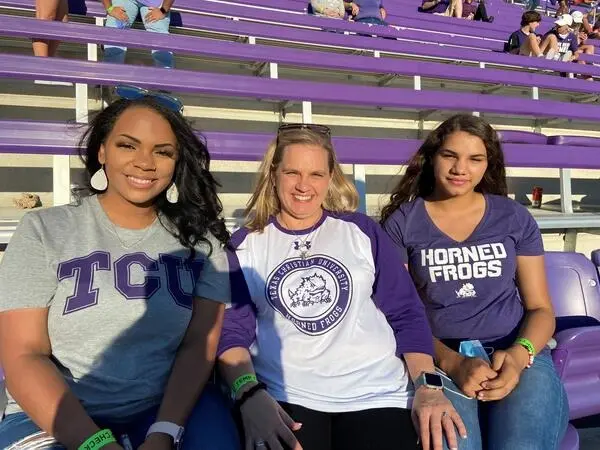
Just twelve days away from the commencement of her senior year at Texas Christian University, Kaylee Webb found herself trapped in an agonizing state of financial limbo. For three years, she had relied on a $19,000 Parent PLUS Loan to help cover the steep costs of tuition, mandatory fees, and room and board at her dream school—the exact institution she had set her heart on attending. Having applied to no other colleges, Webb viewed TCU as her definitive destination, a sentiment now shared alongside her sister Jaci and mother, Katrina. But as the autumn semester approached, the expected financial lifeline simply failed to materialize.
Webb, a computer information technology major, began dispatching frantic emails to the university’s financial aid office, questioning why the parent loan had yet to appear on her account statements. When those digital inquiries went unanswered, she decided to take matters into her own hands. On August 13, she visited the financial aid department in person, hoping for a swift resolution. Instead, she was met with a blunt administrative reality: she was no longer eligible for the funding.
This autumn term marks the first academic year since sweeping legislative changes to federal student loans took full effect following their passage in July. Among the most impactful alterations are strict new limits placed on previously uncapped Parent PLUS and Grad PLUS loans. When the legislation was initially advanced, existing borrowers like Webb and her family believed they would be safely shielded from the cuts due to a legacy provision embedded within the law, as well as the U.S. Education Department’s final rule issued in April. However, those assumptions were upended when federal officials issued a critical clarification regarding the legacy rules in early August.
For Katrina Webb, a middle-class accountant who had closely tracked the evolution of the loan regulations, the sudden reversal felt catastrophic. "We thought we had everything under control with finances," she said.
According to university officials, the Department of Education’s August clarification fundamentally altered how legacy access was calculated. Rather than basing eligibility on the length of time a student had been actively enrolled, the calculation was abruptly shifted to the total number of credit hours a student had completed. Because Kaylee had already exceeded the minimum number of credit hours required to earn her degree—standing at 120—she was suddenly stripped of her legacy protection.
In a formal statement provided to Inside Higher Ed, TCU administrators expressed sympathy for the predicament, noting that while the institution never wants to see a family negatively impacted, "subsequent administrative guidance and rulemaking from the Department of Education changed how loan eligibility is determined." The Education Department, meanwhile, has maintained that the formula for calculating a student’s expected time to credential is not a new policy and should not have caught institutions by surprise.
The blow was particularly painful because half of Kaylee’s accumulated credits came from an associate degree she earned while still in high school—an intentional, cost-saving measure designed to help her get a head start. Katrina Webb described herself as utterly devastated by the outcome, noting that the penalty seemed antithetical to hard work and academic dedication.
"It really feels like someone’s stabbing you when you have a child that tried so hard to do all the right things to make her dream come true," Katrina said. "I’ve talked to several other parents, and all of their kids brought in transfer credits. These are all kids that tried to get ahead, and now they’re being punished. I don’t think that’s fair for any of us when we’re trying our best."
The confusion has been exacerbated by widespread disagreement across the higher education landscape. Not all colleges view the Education Department’s August clarification—delivered informally via a webinar—as legally binding. Major advisory groups, including the National Association of Student Financial Aid Administrators (NASFAA), have acknowledged that they cannot offer blanket guidance to member institutions, instead encouraging individual colleges to consult directly with their own legal counsel before altering student aid packages.
At Loyola Marymount University in Los Angeles, administrators chose a different path. The university announced it would adhere strictly to the department’s final rule published in the Federal Register, which bases loan eligibility on years enrolled rather than credit hours, describing it as the current written interpretation of the law.
"LMU is aware of the Department of Education’s discussion of a different interpretation during its August webinar and is awaiting formal written guidance from the Office of Federal Student Aid before making any changes to its financial aid policies," an LMU spokesperson explained via email.
That institutional stance had immediate repercussions for Kathryn Cook, a business owner and adult learner currently pursuing her Juris Doctor degree through LMU’s evening law program. Cook had expected the federal clarification to work in her favor as she entered the final stretch of her four-year legal education. When the loan-limit rules were first drafted, she was assured she was in the clear. But those assurances evaporated in July.

Because LMU also hosts a standard three-year J.D. program, the university informed students that the Department of Education now requires institutions to use the full-time program length—the shorter three-year timeline—to calculate remaining eligibility for unlimited loans. Having already borrowed up to the newly established $257,500 lifetime limit for Grad PLUS loans, Cook had exhausted her federal options.
When rumors of the webinar’s credit-hour calculation surfaced, Cook initially believed she had found a lifeline. Yet six weeks later, she has received no formal updates from the financial aid office, learning of LMU’s official stance only through the university’s statements to the press. With her autumn tuition bills past due and a formal registration hold placed on her spring semester classes, the pressure has mounted exponentially.
"It’s becoming really stressful for me, because I have a huge chunk of my budget missing," Cook said. "At this point, I’m struggling to pay my rent. And my mom is trying to support me, but she’s a widow. She’s trying to retire. And I’m a first-generation student, so my mom doesn’t really have those resources."
While the specific details and program types vary widely, Webb and Cook represent thousands of students nationwide who are facing unexpected eligibility losses, severe disbursement delays, and acute financial distress as campus financial aid offices struggle to navigate the overhauled federal loan apparatus.
The Education Department and colleges alike faced an extraordinarily compressed timeline to operationalize the new policies following their passage in July 2025 as part of the sweeping One Big Beautiful Bill Act. Industry experts note that the hurried rollout forced financial aid administrators to decipher rapidly evolving and often contradictory guidelines, creating profound confusion that has left families paralyzed over how to fund the remainder of their education.
The Education Department has defended its rollout, arguing that it has delivered robust support to financial aid professionals through conference sessions, published Q&As, webinars, office hours, and dedicated podcasts.
"Not only did the Department implement these regulations on the July 1 statutory timeline, but we published the package two months in advance, providing additional time for schools to prepare," said Ellen Keast, an agency spokesperson.
Rules Change Along the Way
At Saint Louis University, the influx of student and parent inquiries has overwhelmed administrative staff. Alex DeLonis, assistant vice president of student financial services, reported that his office received roughly 5,000 phone calls—a volume matching the historic surge experienced during the chaotic rollout of the redesigned Free Application for Student Aid, commonly known as FAFSA, in 2024. Email volumes followed a similarly punishing trajectory.
"We thought FAFSA simplification might have been an anomaly, but to have two pieces of legislation that have completely flipped things upside down and we’ve had to implement so closely together—it’s just a lot," DeLonis said. "It’s hard to predict and plan when the rules change along the way."
In response, SLU has attempted to deploy stopgap measures, offering supplemental emergency grants and institutional loans to bridge the gap for students whose federal aid has been abruptly curtailed. However, university leaders acknowledge that such internal remedies are neither universally available nor sustainable as a long-term fix.
The confusion extends far beyond outright denials of PLUS loans. Other students maintain theoretical eligibility but remain deeply uncertain about how much borrowing time they have left. Many are wrestling with intricate proration provisions that tie borrowing caps directly to active credit-hour enrollment, while others struggle to understand shifting federal definitions of what constitutes a recognized professional degree.
Adding to the administrative gridlock, many college financial aid offices have been forced to manually update software systems or perform calculations by hand because third-party software vendors have been unable to keep pace with the continuous stream of federal guidance. These compounding obstacles have routinely delayed the actual disbursement of funds, even for students who technically remain eligible.

"What we hear is a general sense of anxiety that the rules are shifting faster than the financial aid system can keep up," said Mike Pierce, executive director of the student advocacy group Protect Borrowers. "The student loan system and America’s higher education finance system are really not built to handle this kind of change."
Karen McCarthy, vice president of federal relations at NASFAA, pointed to the structural origins of the crisis, citing the intrinsic complexity of the legislation combined with the severe time constraints imposed on implementation.
"What we are seeing now is the impact of not following that master calendar," McCarthy said, referencing the department’s traditional protocol of finalizing regulations by November 1 to give institutions a full academic year to prepare for systemic shifts.
Conversely, Keast noted that an advisory committee formally signed off on a draft of the regulatory changes in November 2025. "If institutions waited until the final rule was issued to start preparing, that was their decision," she said, though financial aid administrators were not formally represented on that committee.
Feeling Abandoned
After weeks of harrowing uncertainty, Kaylee Webb’s immediate academic future at TCU has stabilized. Now a full month into the fall semester, she has received her official class ring and is actively planning her senior portraits.
"I’m still super ecstatic to be graduating from TCU," she said. "Like I said, it’s the only place I wanted to go, and it’s the little things along the way that help lighten the mood."
Yet the resolution came at a high cost to her peace of mind. For a brief window, she questioned whether she would be permitted to finish her degree at all. Ultimately, with the guidance of TCU’s financial aid office, the family discovered an alternative funding source through a private loan program administered by the Texas Higher Education Coordinating Board known as the College Access Loan. Because Kaylee maintained a part-time job and a strong independent credit score, she qualified for the financing on her own, avoiding the need for parental co-signers.
"As a parent, I was trying to keep all the loans that I could out of Kaylee’s name," Katrina Webb reflected, noting that private loans lack the income-driven repayment and forgiveness safety nets built into federal student loan programs. Still, she takes comfort in knowing her daughter will walk the stage, build her professional résumé, and enter the workforce with clear employment ambitions.
For students like Kathryn Cook, however, private loan alternatives are simply out of reach. She continues to search desperately for viable solutions, but acknowledges that if current financial hurdles persist, she may be forced to take an involuntary leave of absence from law school. While she could theoretically complete her legal training and sit for the bar via California’s traditional apprenticeship pathway, the prospect offers little comfort.
"I’d still be having to pay for a degree that I never got," she said.
Both families express empathy for the difficult positions occupied by campus financial aid workers who were handed an impossible timeline by federal regulators, but their overarching sentiment remains one of deep frustration.
"I feel really kind of abandoned, especially from the lack of communication. It’s worn me out," Cook said. "It’s just so unjust. I feel like I need to continue telling people how it’s affecting me so they can fix it."