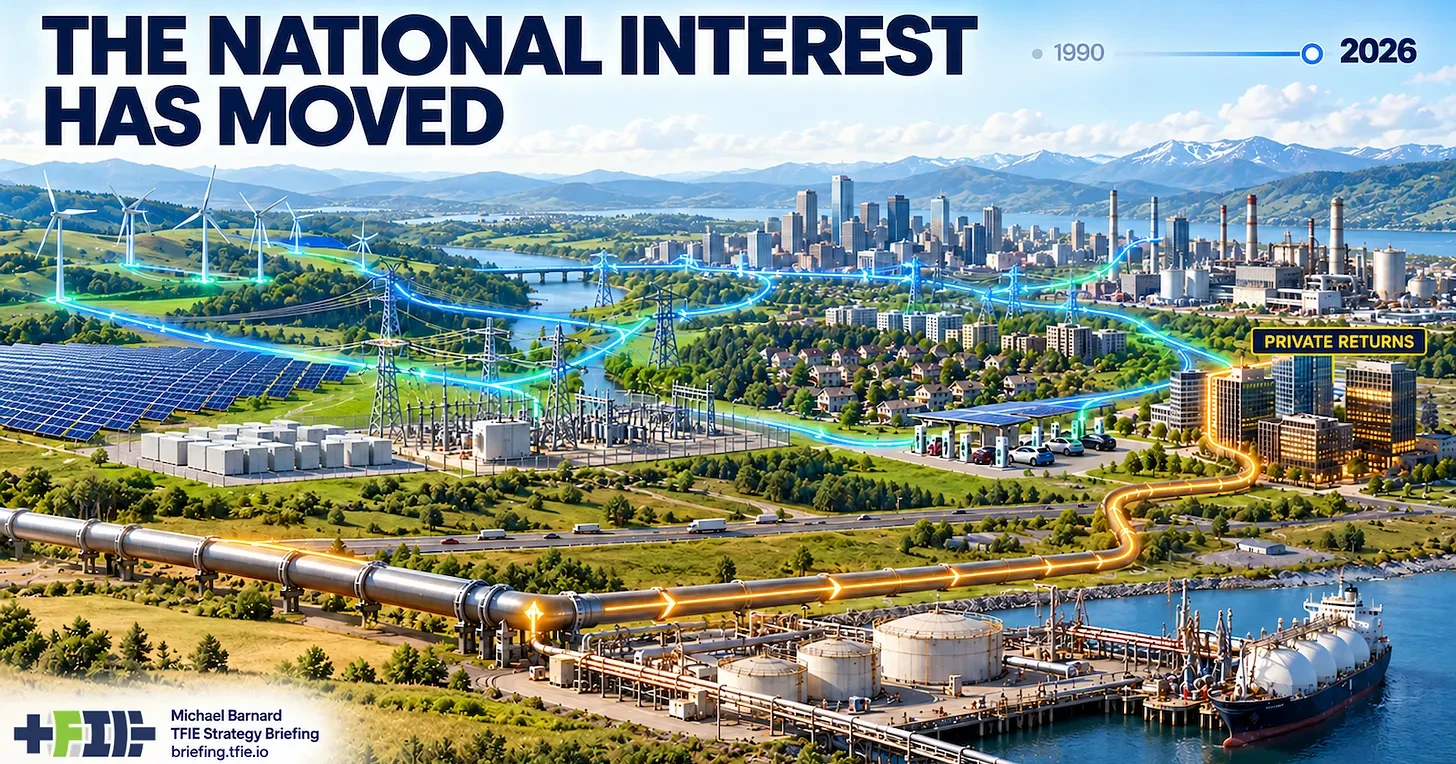
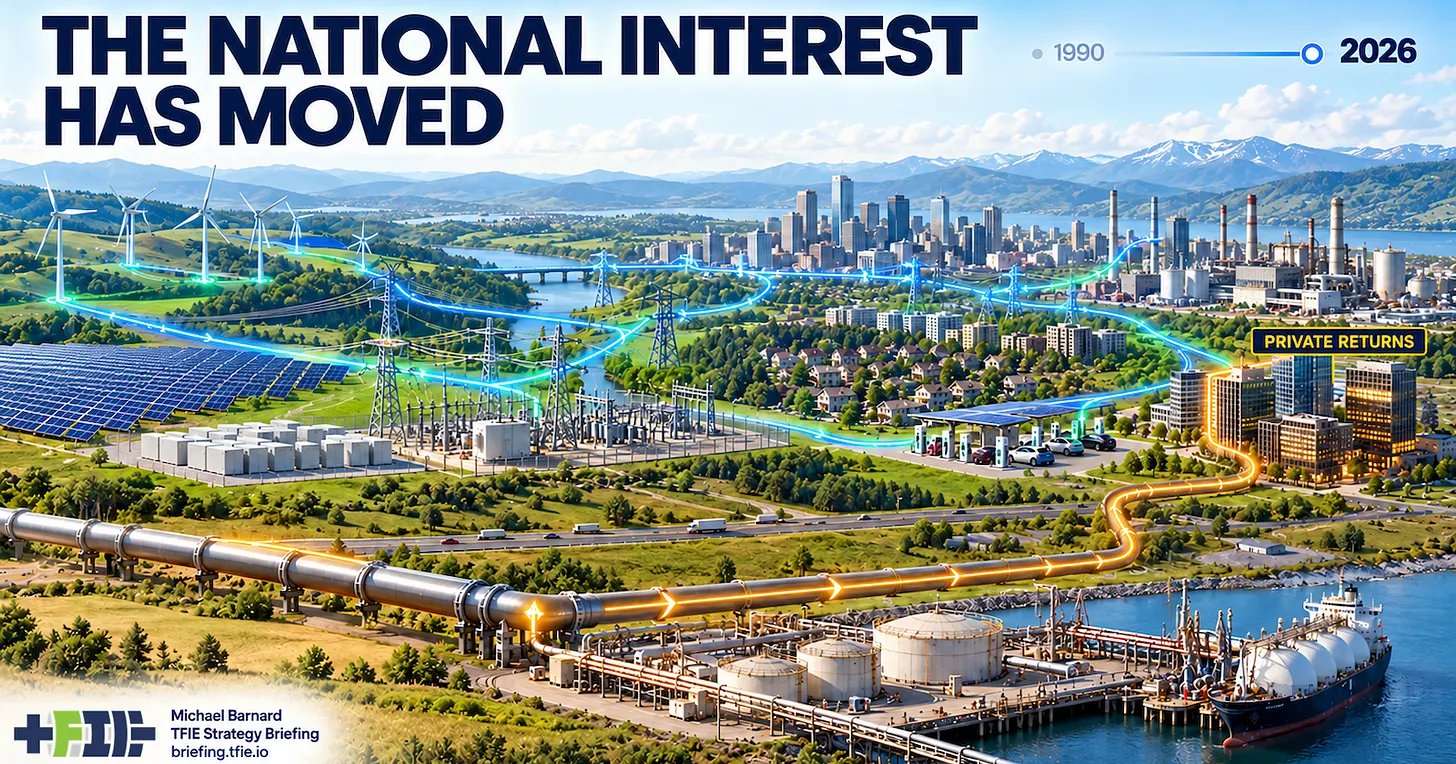
The national energy calculation has officially shifted. For much of the modern climate-policy era, national self-interest and climate action could plausibly point in opposing directions. A country could afford to let other nations shoulder the financial burden of emissions reductions while continuing to rely on familiar, entrenched coal, oil, and gas infrastructure at home. When low-carbon alternatives were expensive, limited, or technologically immature, maintaining the status quo could often look economically rational—even if it externalized severe climate costs onto the rest of the world.
However, the technological and economic choices available today are fundamentally different, suggesting that this old ledger deserves a rigorous second look. Solar power, wind turbines, and energy storage batteries have fallen sharply in cost over the past decade. Electric vehicles have matured into mass-market products across many major economies, highly efficient heat pumps are increasingly capable of replacing fossil-fuel combustion in a large share of residential and commercial buildings, and advanced power electronics have dramatically widened the range of industrial and consumer equipment that can run efficiently on electricity. A government minister deciding what kind of energy infrastructure to build today is choosing from an entirely different technology set than a minister making the exact same choice in 1990.
This stark contrast between two distinct technology eras forms the foundation of recent strategic analysis exploring the shifting dynamics of national interest and private energy incentives. While energy simulation tools and economic models continue to evolve, the more pressing and practical question for policymakers is whether the hard economics unfolding outside these models point in the same direction.
For fossil-fuel importing nations, the answer is increasingly affirmative. Imported fuel must be bought and paid for repeatedly, meaning that continued dependence exposes a country to volatile global commodity prices, geopolitical pressure from foreign suppliers, and unpredictable foreign exchange rates. In contrast, a strategic pivot toward electrification shifts a much larger share of national spending upstream into domestic power generation, robust transmission networks, and durable equipment that continue providing essential services long after the initial capital expenditure has been paid off.
Yet, this transition is by no means free or frictionless. Cheap solar panels can be exceptionally valuable where electrical grids are weak, unreliable, or entirely absent, allowing households, small businesses, and heavy industrial sites to generate their own power directly behind the meter. At a utility scale, however, low module manufacturing costs only translate into low-cost delivered electricity if grid infrastructure, system flexibility, and affordable financing keep pace with deployment.
Similarly, households require adequate access to capital before the long-term lifetime savings offered by electric vehicles or heat pumps can actually become available to them. Transmission lines, distribution networks, grid-scale storage, flexible demand management, and affordable capital are not optional extras to be bolted on after a generation technology has been chosen; they are core components of the fundamental economic comparison.
This structural reality helps explain why the national energy calculation varies so dramatically from one country to the next. Importers can systematically reduce recurring fuel expenditures and dangerous local air pollution as they electrify their economies. Fossil-fuel exporting nations, conversely, may still depend heavily on oil and gas revenues to fund public budgets, support local jobs, and sustain regional economies. For these exporters, building out clean domestic electricity does not automatically replace lost export income. Furthermore, countries facing persistently high interest rates can find that inexpensive generation equipment quickly translates into expensive electricity once financing costs are fully factored into the equation.
Time introduces yet another layer of complexity to the policy challenge. Constructing new grid infrastructure can drive substantial economic activity well before the promised energy savings begin to materialize, while higher short-term electricity rates may be immediately visible and painful to voters. Cleaner ambient air can dramatically improve public health outcomes without ever appearing prominently in traditional gross domestic product statistics, and households asked to purchase advanced clean equipment experience the heavy upfront capital cost long before their operating savings accumulate.
These fundamental economic differences create ample room for private commercial incentives to diverge from the national ledger. A legacy fuel supplier naturally benefits when consumer and industrial demand for fuel persists, a traditional utility may earn guaranteed regulatory returns from constructing another conventional infrastructure asset, and a fossil generator may be paid handsomely simply to remain available on standby. Companies do not need to be behaving improperly or maliciously for their legitimate commercial interests to favor extending the lifespan of legacy assets that still generate reliable revenue.
The exact same critical test must be applied to the industries building the replacement clean energy system. Renewable energy developers can aggressively seek out generous guaranteed pricing structures, clean tech manufacturers can attempt to shape industrial subsidies exclusively around their own proprietary products, and transmission companies can sometimes favor capital-intensive construction where smarter storage deployment or operational software changes might solve part of the problem more cheaply. Furthermore, domestic industrial policy can easily backfire and raise consumer costs when trade protectionism is treated as an end in itself rather than a tactical tool for fostering market capability.
Good energy policy increasingly depends on rigorously comparing these competing interests against tangible, delivered outcomes. Forward-thinking grid planners can publish transparent forecasts and test the economic value of new wires against energy storage, flexible demand response, and better utilization of existing physical infrastructure. Utility regulators can shift their focus to reward system reliability, connection speed, and customer cost reduction rather than rewarding capital spending volume alone. Public financial support can be tied to strict performance milestones and sunset dates rather than becoming permanent simply because a particular industry learned to depend on government largesse.
Households remain the ultimate practical test for any energy transition. Lifetime economic models are of little practical help to a commuter who cannot secure financing to buy an electric vehicle, an apartment tenant who does not control their building’s heating system, or a lower-income household asked to absorb higher near-term electricity bills while the broader power system is being rebuilt. Careful sequencing, broad access to affordable finance, and targeted social protections can determine whether an economically sensible transition remains politically sustainable over the long term.
The classic international climate free-rider problem has not disappeared. Countries can still benefit from emissions reductions achieved elsewhere while doing relatively little within their own borders. What has fundamentally changed, however, is that many fossil-fuel importing nations can now severely damage their own national economic interests at the same time by holding onto expensive fuel dependence and delaying necessary investments that could reduce it.
Ultimately, this leaves governments facing a far more demanding set of questions than simply determining whether a given technology happens to be labeled clean or incumbent. Policymakers need to examine what useful service an investment actually delivers, who pays the bills before the benefits arrive, who stands to profit financially if climate action is delayed, and what empirical evidence will prove whether the policy decision ultimately worked.